This chart from ETR’s AI Buyer survey (n=200) jumped out: 62% already using Claude + 28% in pilot/evaluation = 10% remaining true new-logo whitespace!
That is a provocative framing that surely over-penalizes Anthropic for its success → implying a limited greenfield early in the AI epoch is ridiculous!
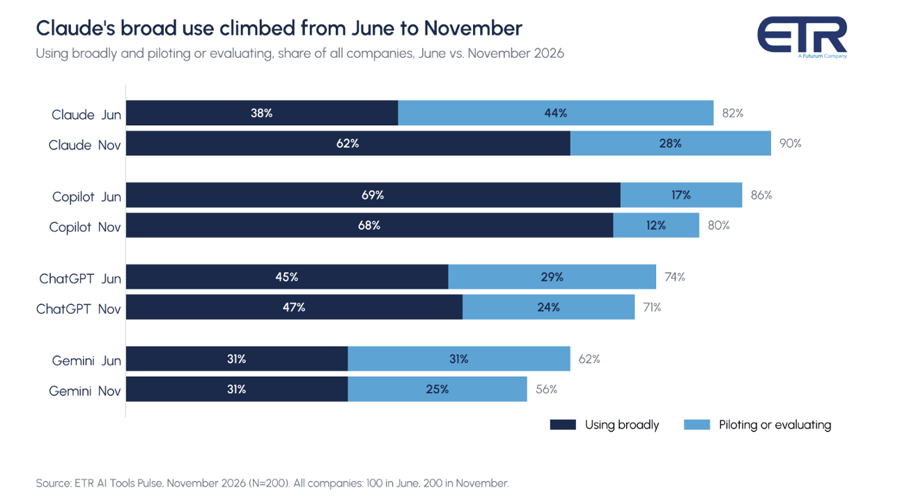
That said, it does highlight how Anthropic’s growth path will depend heavily on expansion/NRR rather than new logos.
Anthropic Customer Slope → The Path To $100 Million ACV Customers
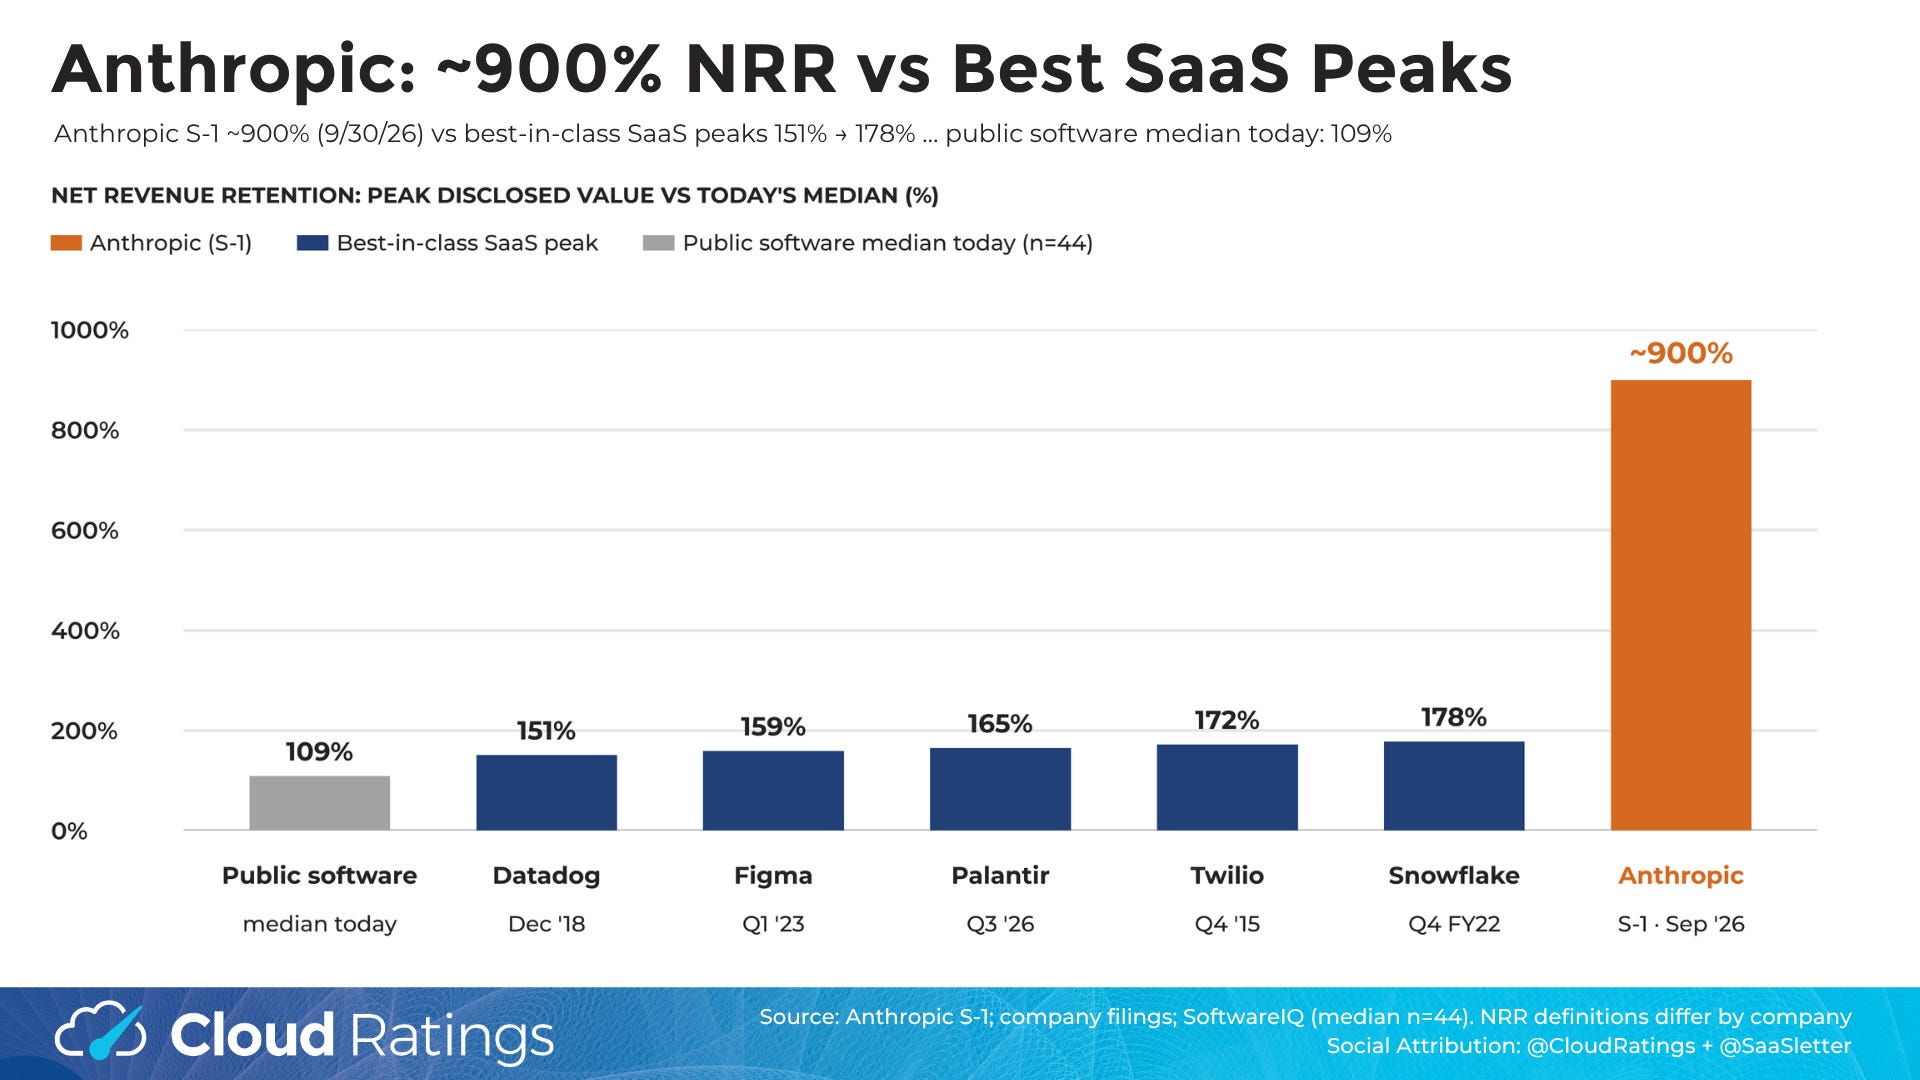
The 900% NRR(!) disclosed in Anthropic’s S-1 is insane. Granted, against an “easy comp” (mentally, it’s easy to forget how vertical ANT has gone in 2026 relative to 2025 when OpenAI dominated the narrative).
Peak NRR for best-in-class expansion motions has been in the ~150%-~180% range.
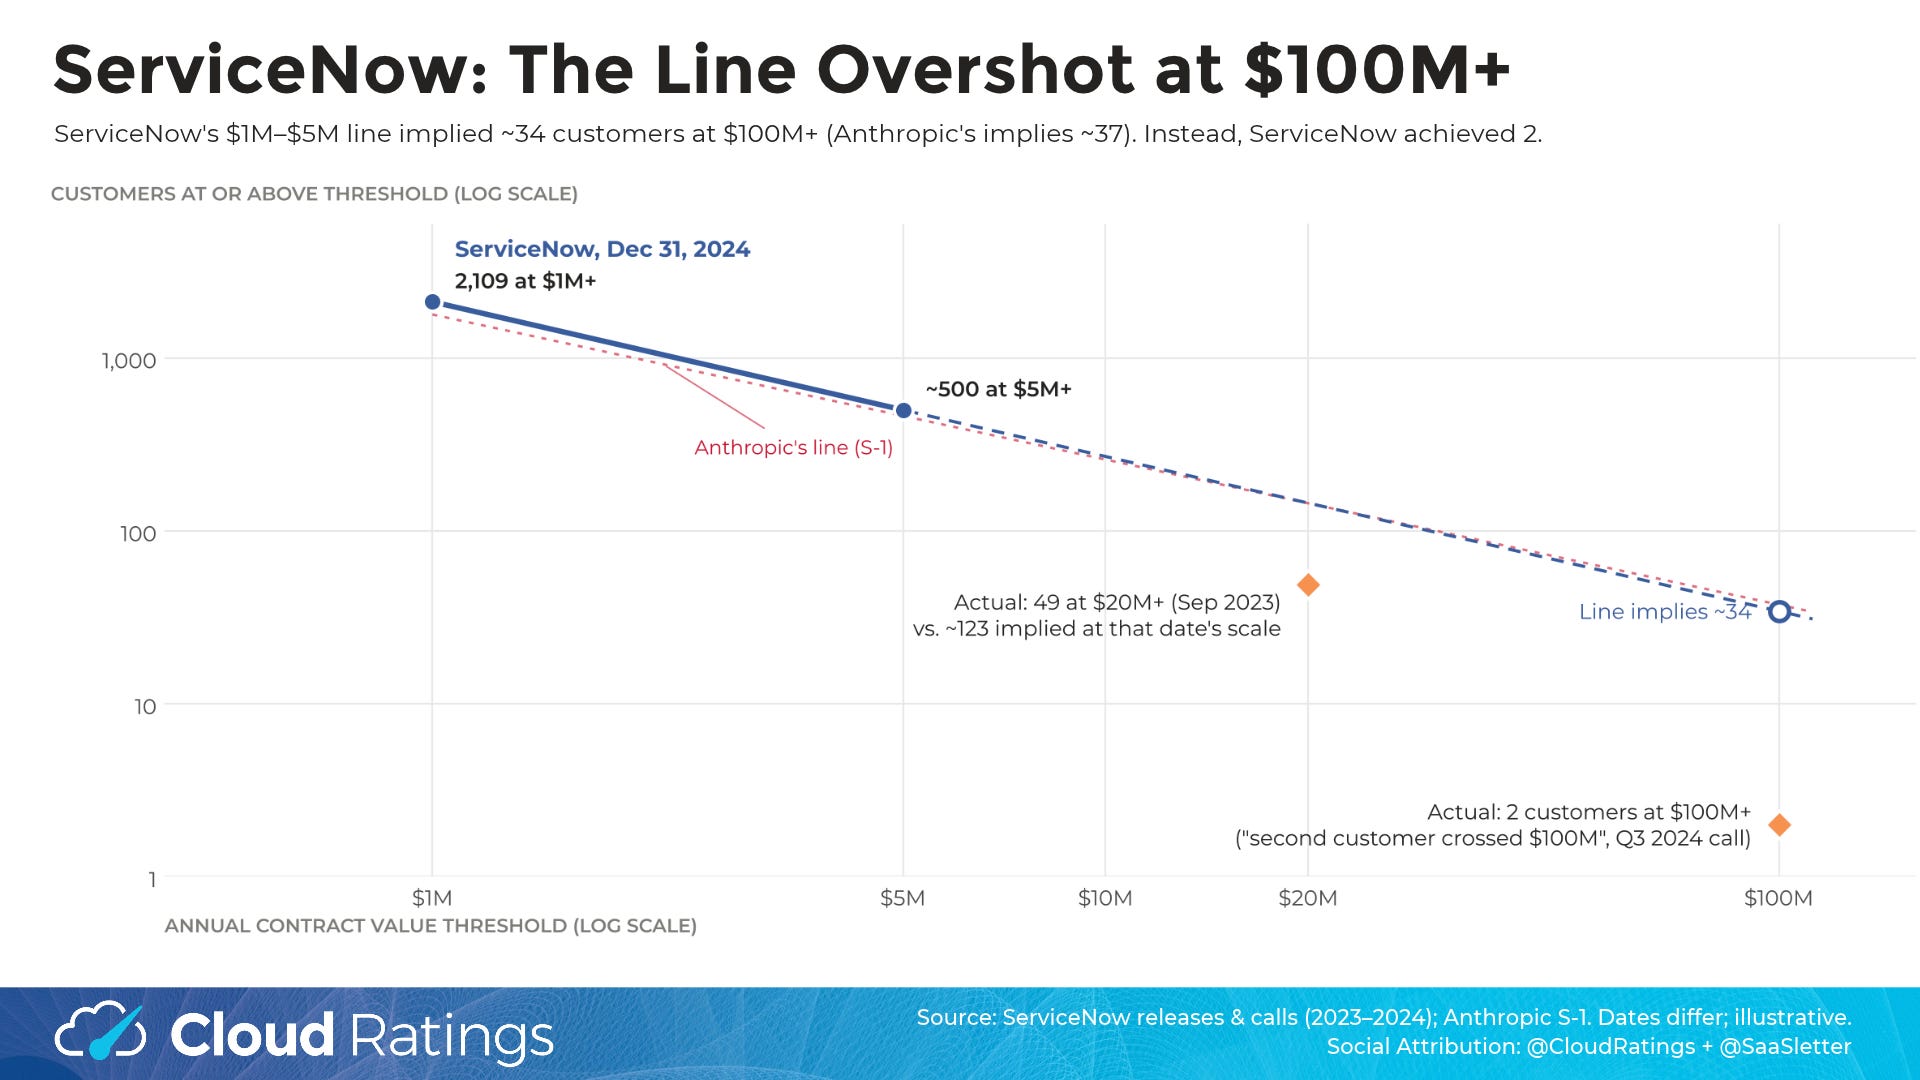
Their S-1 also disclosed their customer mix. The trendline to 37 $100m+ Anthropic customers is OUR ESTIMATE.
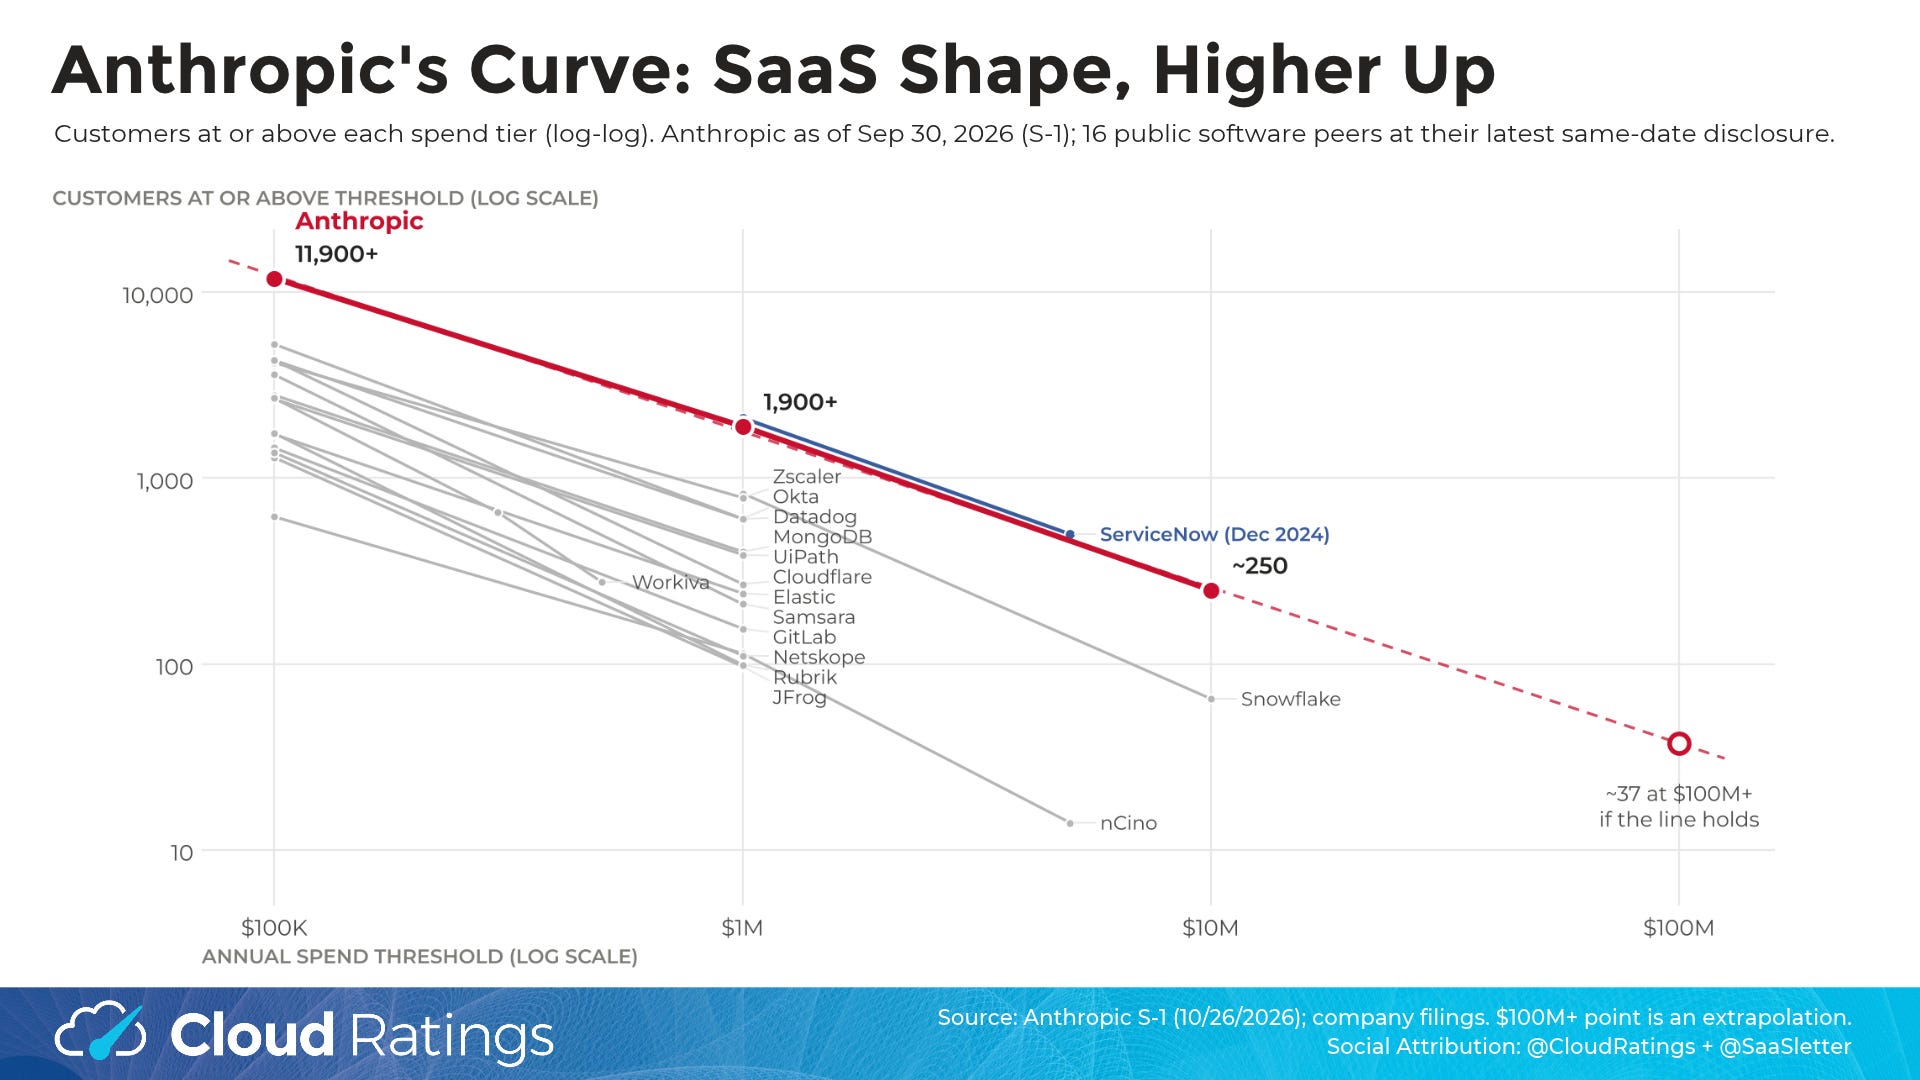
With today’s benchmarks versus software here:
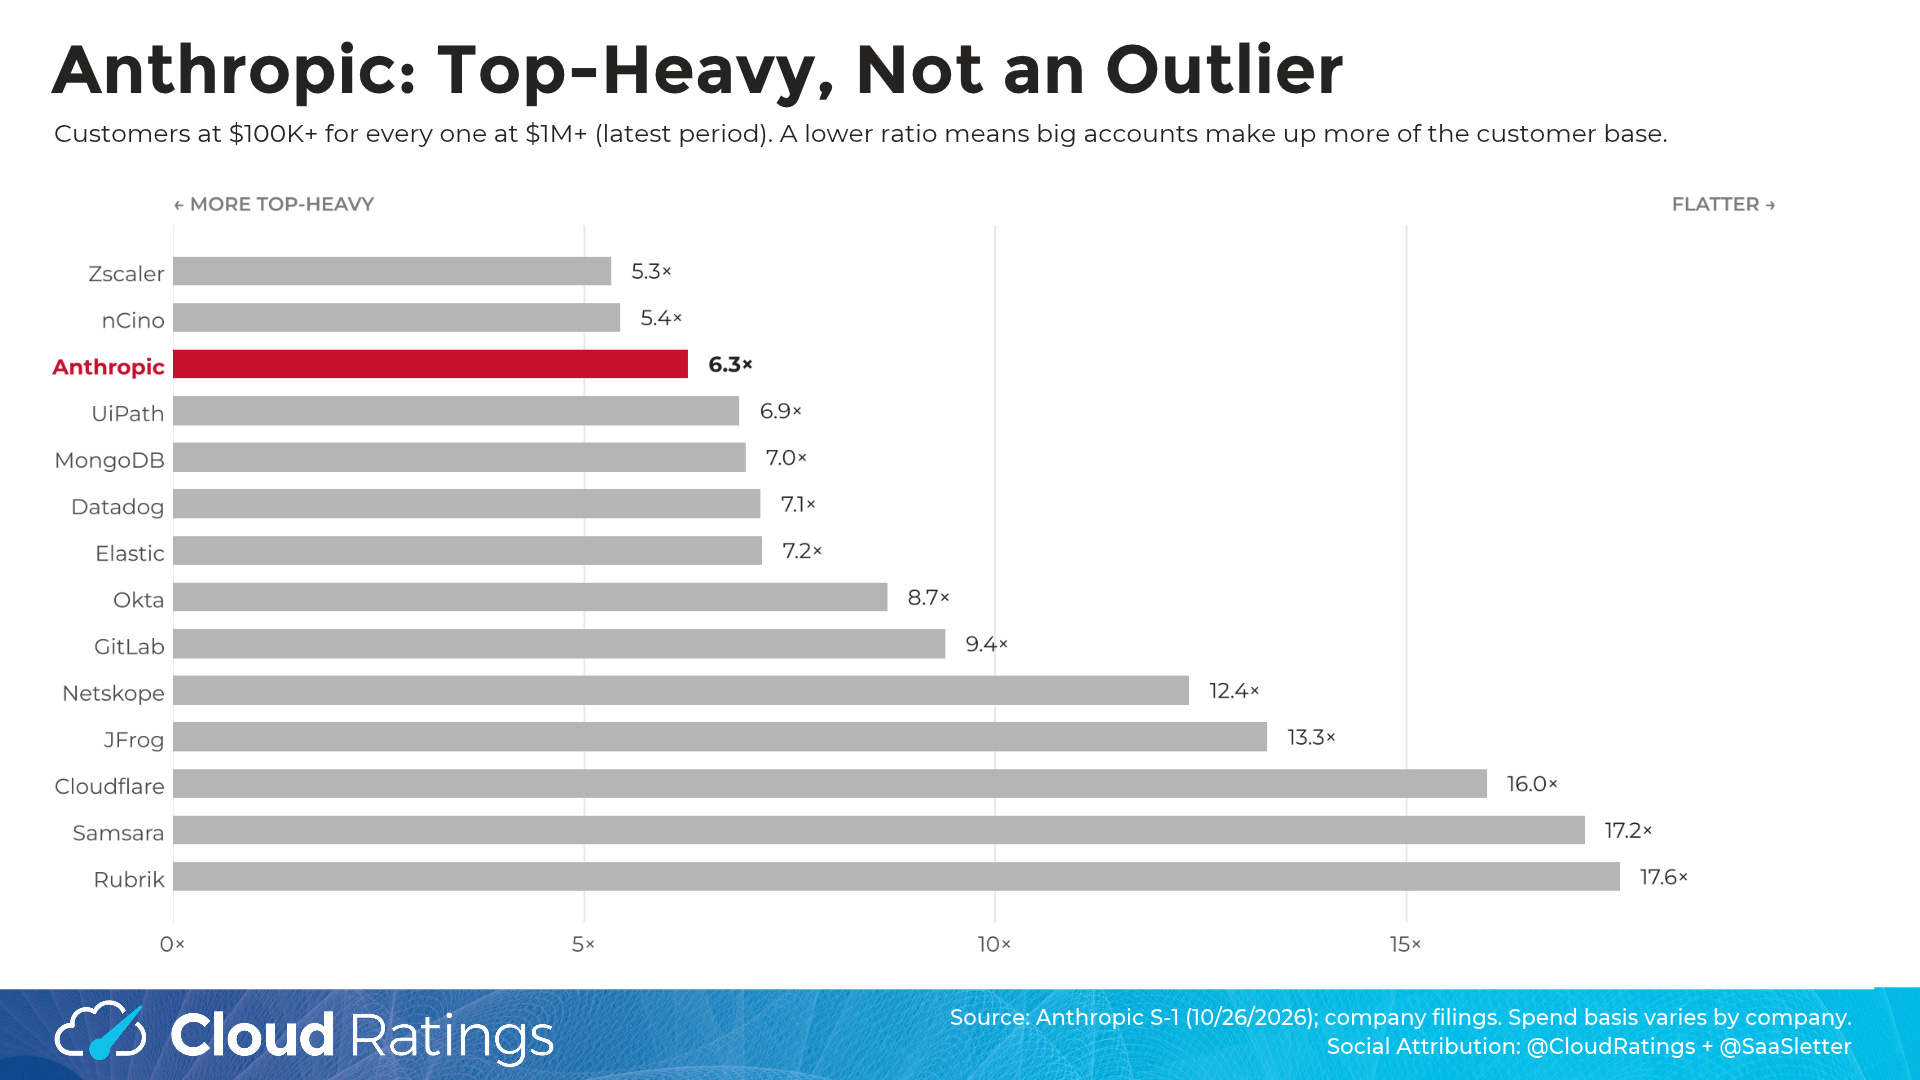
Interestingly, the broader software industry has been moving towards a top-heavy mix (see also “Top Heavy Symptoms” section below):
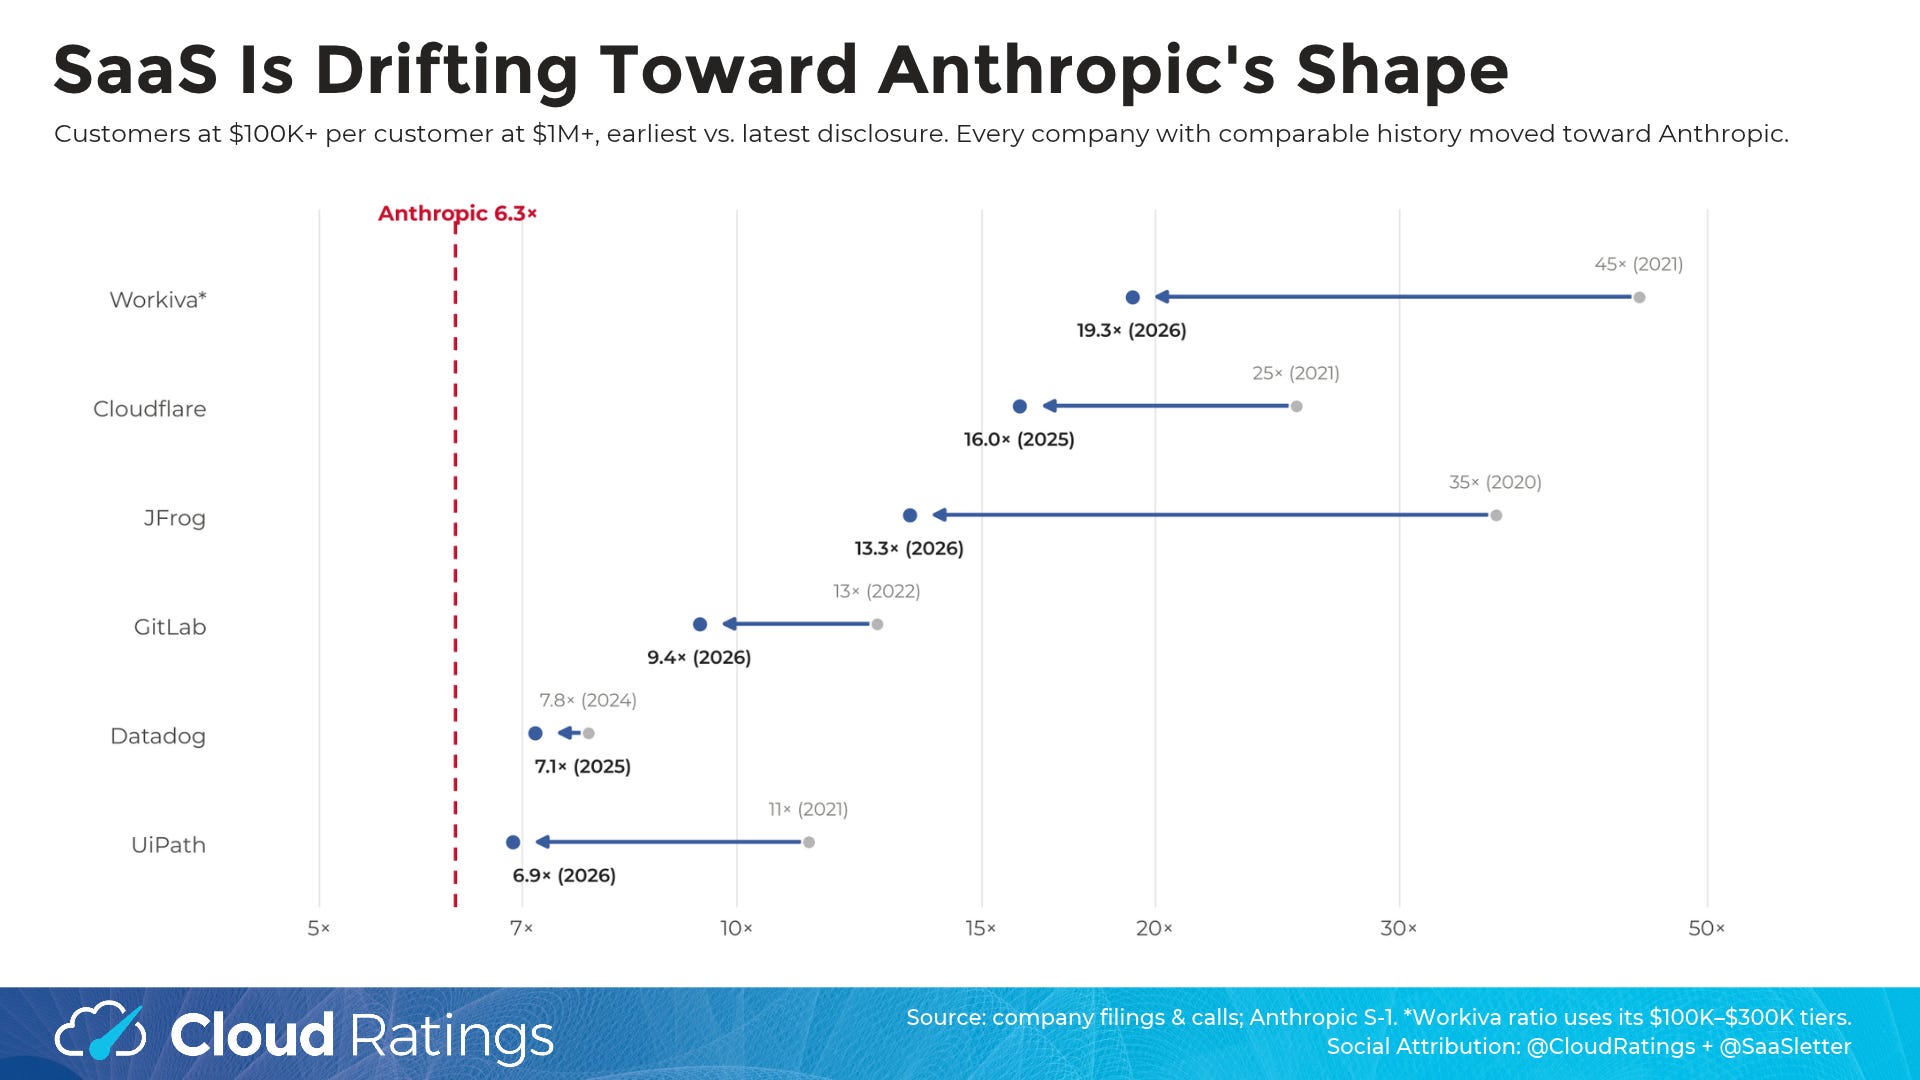
Given the novelty + especially risk profile of AI, we view Anthropic’s ability to sign new logo deals in the $100 million range as improbable.
Getting to $100m ACV will need to come from expansion. Via taking on more workloads, more products, expanding into more divisions and LOBs, more channel partners + systems integrators, and (sadly likely) labor replacement.
The one track record we have for this $100m path is ServiceNow. With critical caveats: application software = different model (less infrastructure-style upside embedded in Anthropic’s API revenue line).
That said, ServiceNow did not hit the $100m curve. To their credit, they have generated a 28.4x post IPO return:
Setting Context On Big Deals, Mega ACV Customers
ServiceNow arguably has the best disclosure history for mapping its mega-customer journey. Relative to a corporate history of:
Founded in 2004 in San Diego (my hometown, our headquarters. I fondly remember playing basketball outside NOW’s early “Spaceship” office RIGHT at the beach → Founders + VCs: maybe a lesson in going nicer on offices!).
Series C with Sequoia in 2009.
IPO in 2012 = 28.4x return at Friday’s close. 28.4x!
Revenue Milestones:
$1b revenue in 2015 (~12 years after founding)
$5b in 2021 ($4.5b in 2020, the year its largest customer crossed $40m ACV)
$10b in 2024 ($11.0b) → same year as its first $100m+ ACV customer
$13.3b in 2025
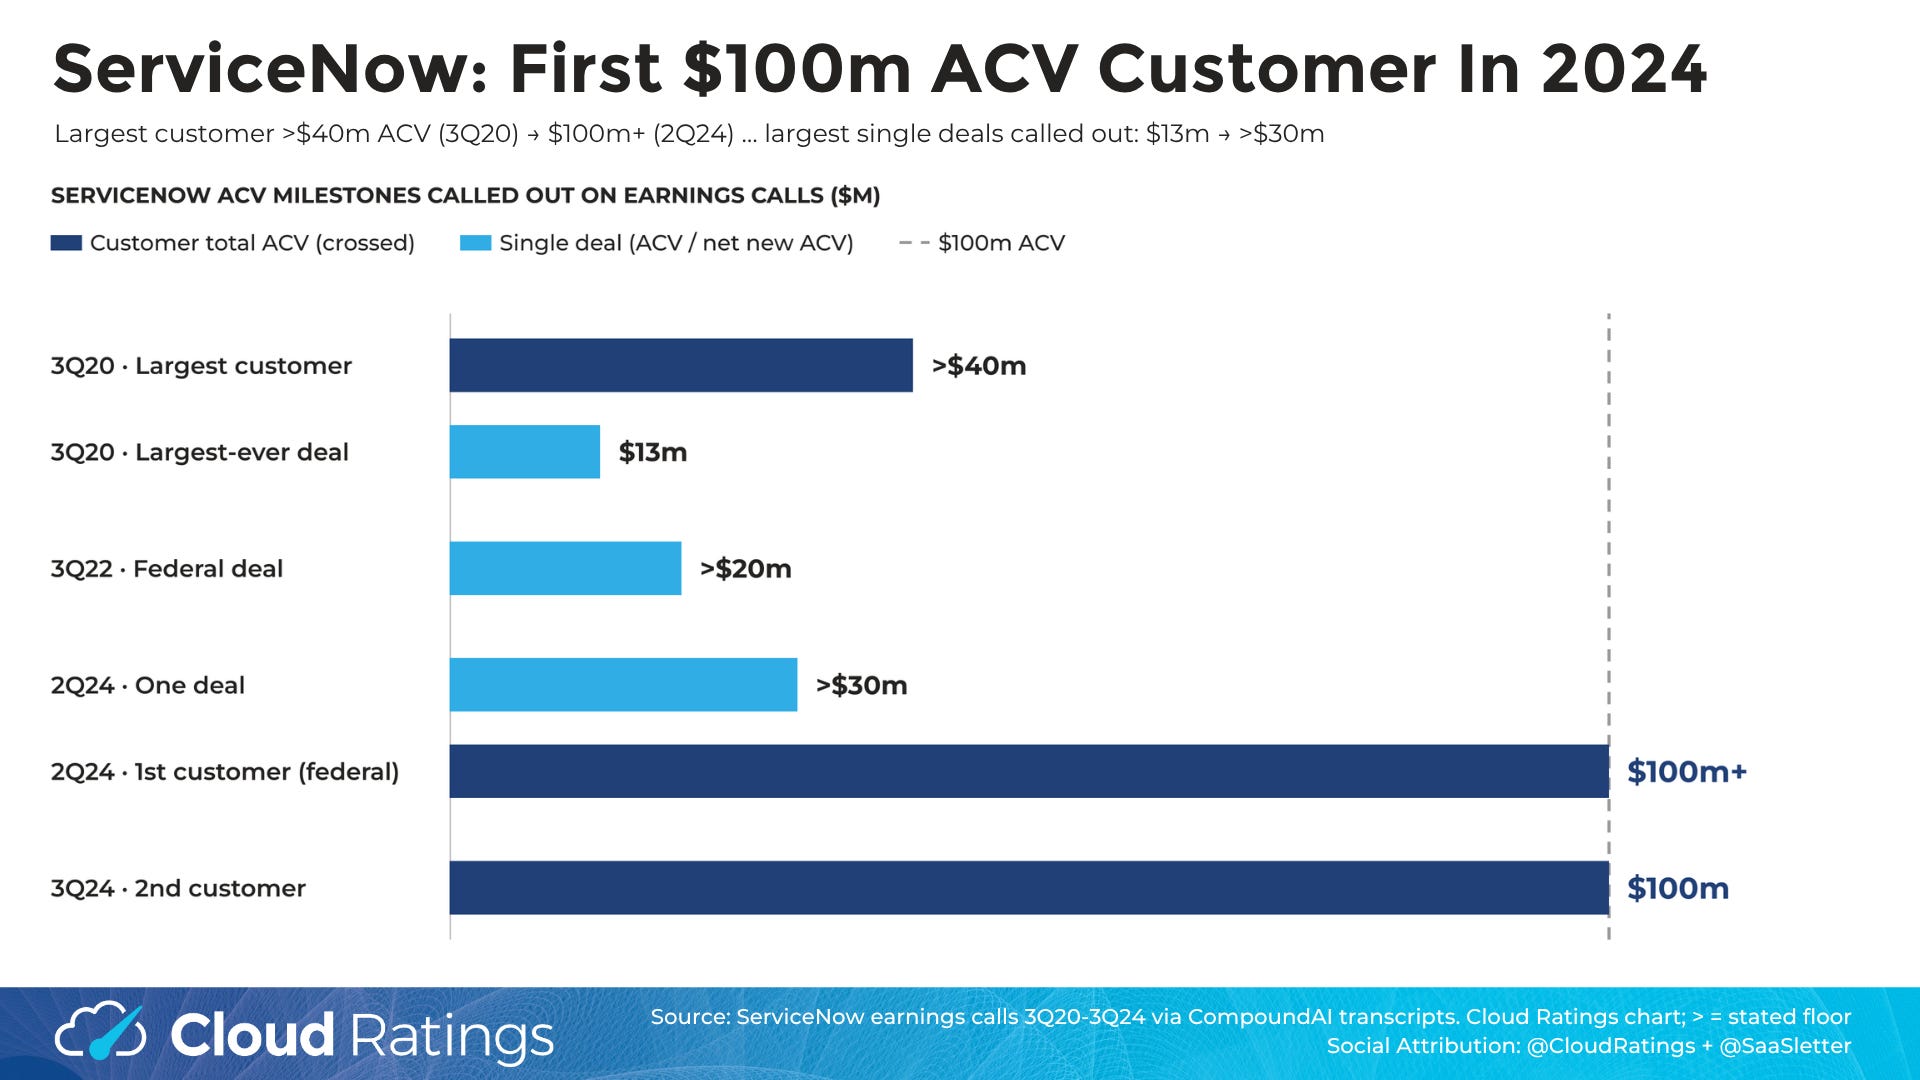
Note: the color differences between customer total ACV (dark blue) vs. single deal / net new ACV (light blue).
With supporting earnings transcript quotes:
ServiceNow:
“We landed our largest deal ever with our largest customer who has now crossed over $40 million in ACV.” - Q3 2020 Earnings Call - Oct 28, 2020
“Our first federal customer actually crossed the $100 million+ ACV threshold, and we signed our third-largest net new ACV deal ever.” - Q2 2024 Earnings Call - Jul 24, 2024
Beyond NOW, a historical sample of large deal callouts across large-cap software:
Salesforce:
“…we’ve never done more than 10 deals above $10 million in any given quarter.” - Q4 2026 Earnings Call - Feb 25, 2026
“…the US Air Force, which, by the way, just signed a new $72 million ELA with us during the quarter.” - Q1 2027 Earnings Call - May 27, 2026
MongoDB:
“We signed several large deals in the quarter, including an approximately $90 million transaction with a large tech company that plans to expand both core and AI workloads on Atlas, and a greater than $100 million transaction…” - Q4 2026 Earnings Call - Mar 2, 2026
Cloudflare - Speaks to how notable deals can be quite small:
“One of the largest and oldest European financial services firms signed a three-year deal worth $450,000 per year for Cloudflare for Teams…” - Q2 2020 Earnings Call - Aug 6, 2020
Oracle:
“…it would be an odd quarter when we didn’t sign a single deal for over $1 billion, and we have multi-billion dollar customers.” - Financial Analyst Meeting - Sep 2023
The Oracle “single deal for over $1 billion, and we have multi-billion dollar customers” highlights the limitations of THIS newsletter's big-deal recap—limited coverage of right-tail-heavy platforms like hyperscalers (Azure / Google Cloud / AWS) and other large caps that disclose less.
Related: Anthropic Sales + Marketing Margin Targets
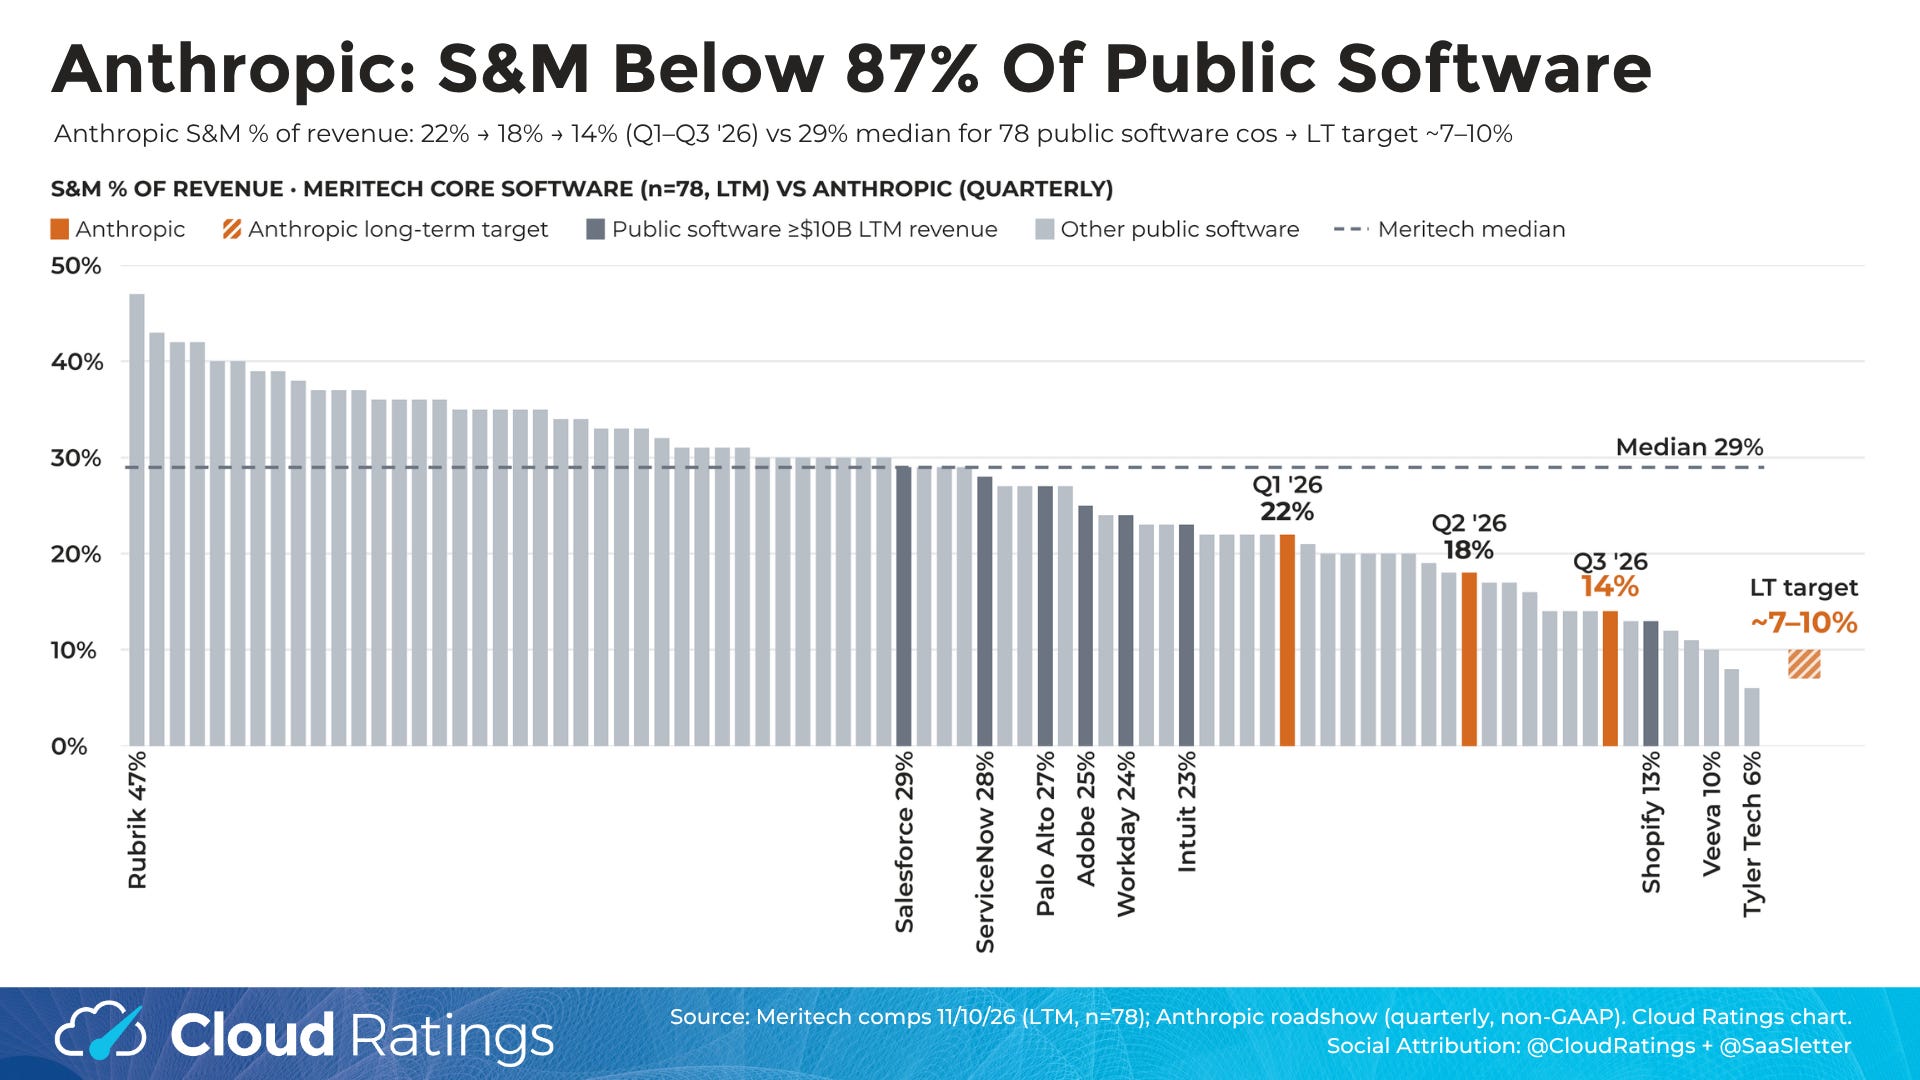
Anthropic’s IPO roadshow disclosed their long-term Sales + Marketing margin targets at 7%-10%. In visual form here to set up the key mega-expansion-related point: