

Before we get into our AI-driven churn coverage, we’re excited to announce an upcoming virtual event:
“Accurate Insights 2026” Event - RSVP Now
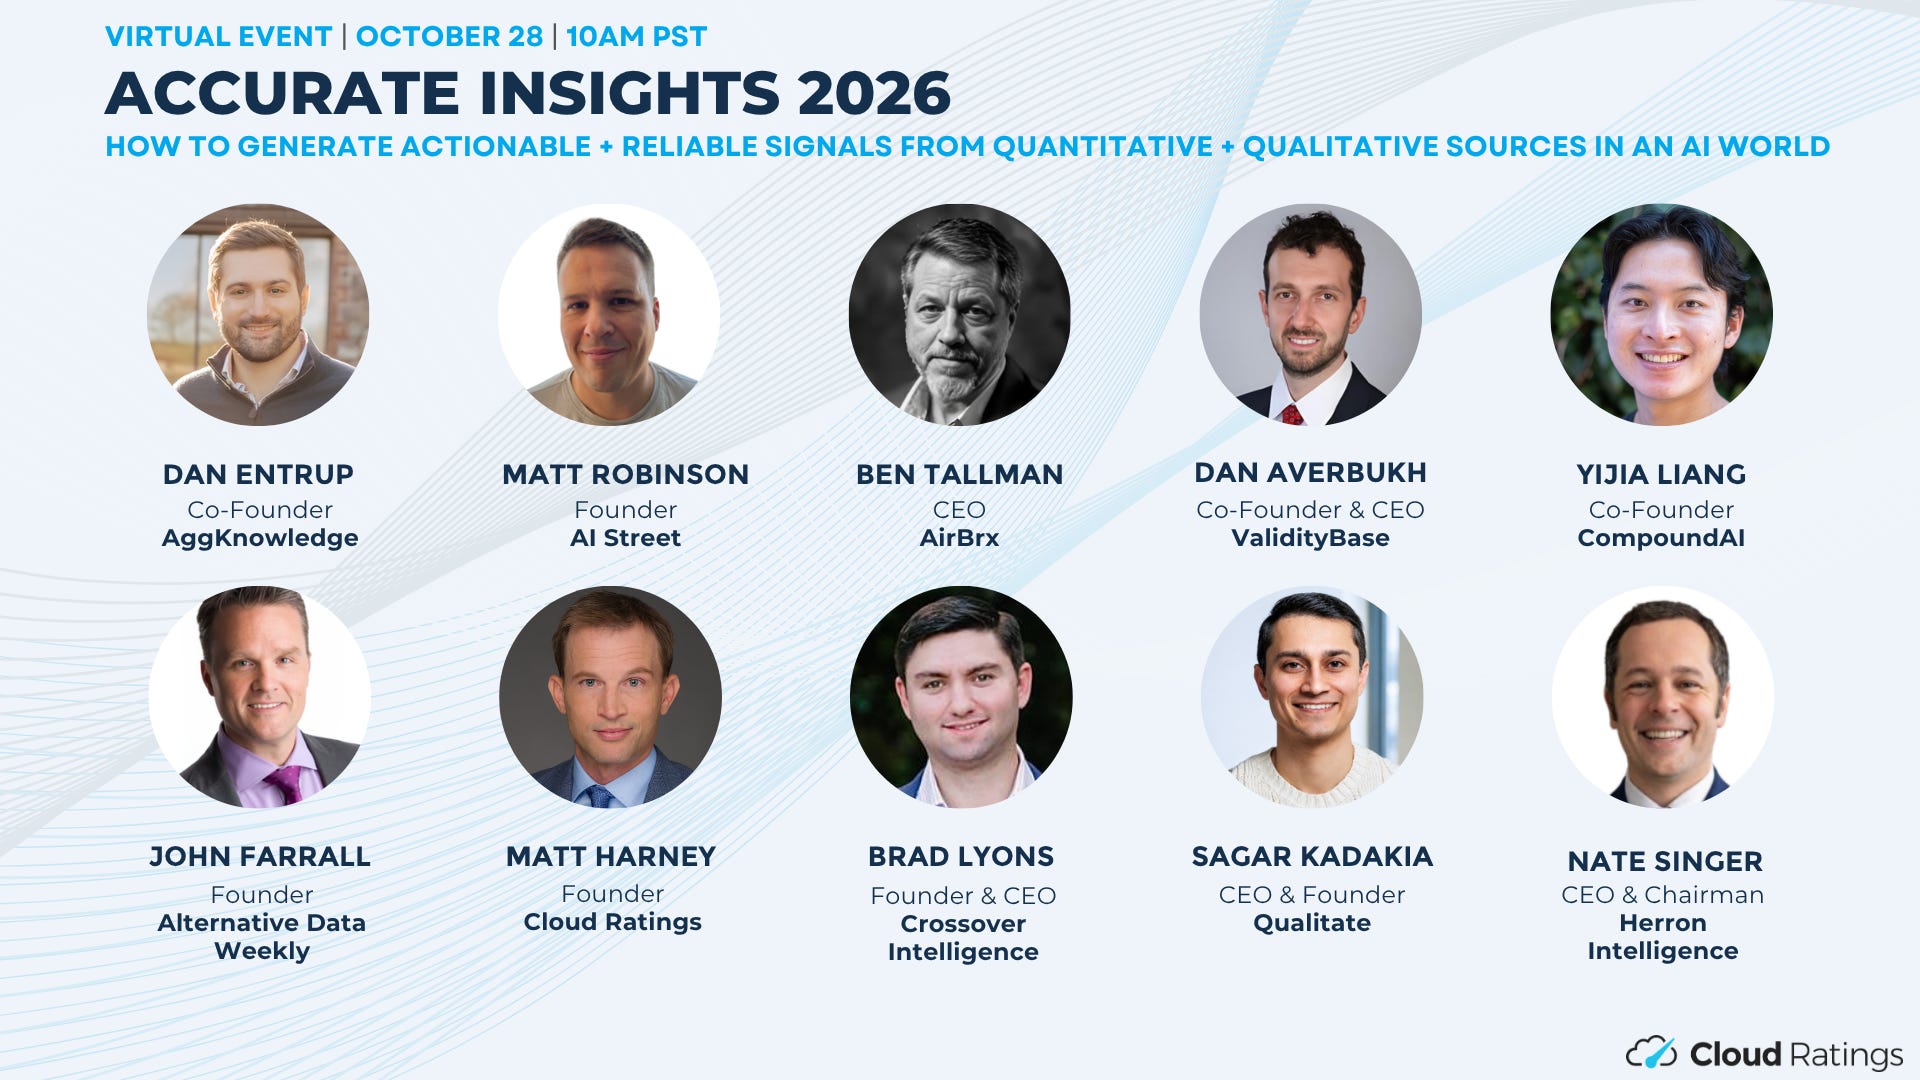
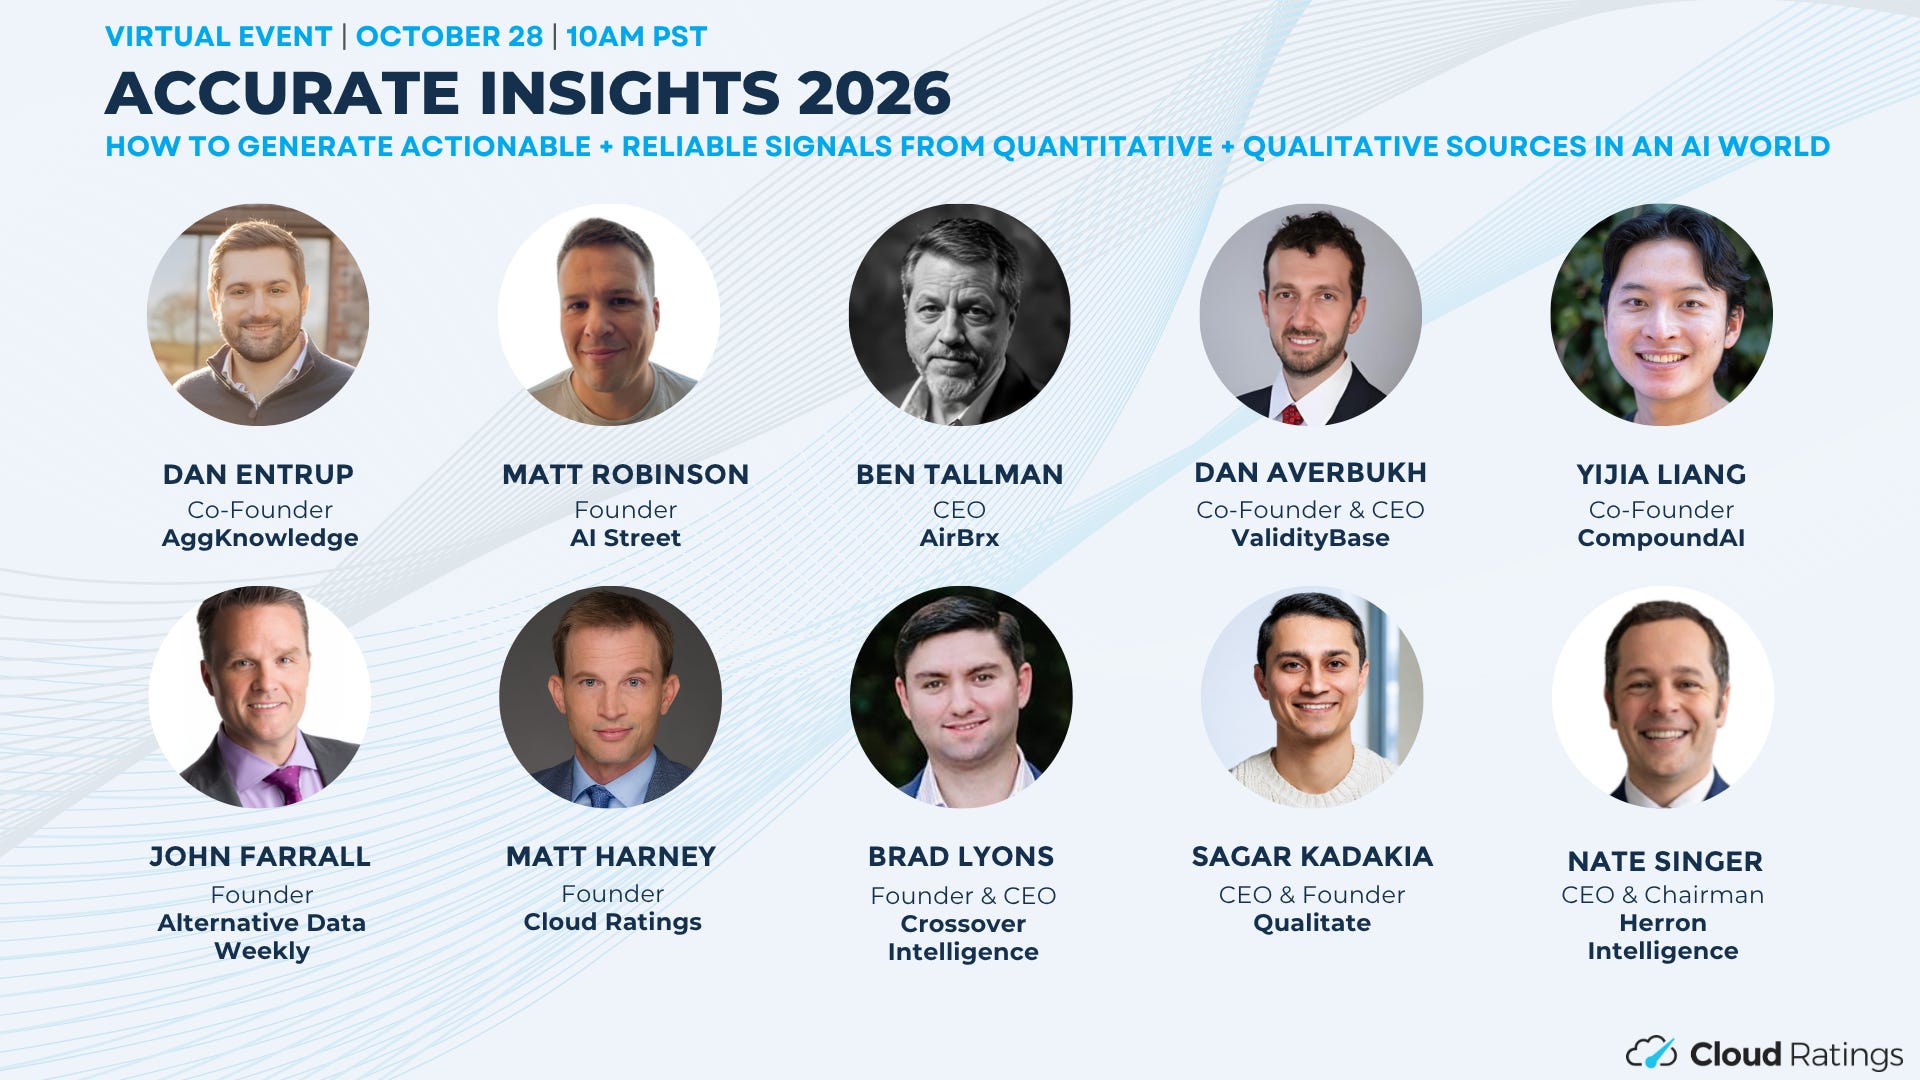
Curated for institutional investors, the event will focus on generating actionable, reliable signals from quantitative and qualitative sources in an AI world.
With perspectives from these expert speakers:
Dan Entrup - Co-Founder - AggKnowledge
Matt Robinson - Founder - AI Street
Ben Tallman - CEO - AirBrx
Dan Averbukh - Co-Founder & CEO - ValidityBase
Yijia Liang - Co-Founder - CompoundAI
John Farrall - Founder - Alternative Data Weekly
Matt Harney - Founder - Cloud Ratings
Brad Lyons - Founder & CEO - Crossover Intelligence
Sagar Kadakia - CEO & Founder - Qualitate
Nate Singer - CEO & Chairman - Herron Intelligence
AI-Driven Churn → Qualitate New Report
We invited Qualitate CEO Sagar Kadakia to speak at “Accurate Insights 2026” because of the caliber of their research work product, including their new “The AI Disruption Report” (56 slides | n=4,800+).
Their definitions are key to interpreting and commenting on the report:
“Displacement is used to describe plans for true negative actions or diminished Usage of a particular company - defined as instances of Spend Decreases and Churn, without Spend Flattening.”
“Disruption is a broader term that also includes flattening NTM Spend, to gauge vendor stagnation. We define Disruption as instances of Spend Decreases + Churn + Spend Flattening.”
Key excerpts:
AI-Driven Displacement 1H 2026 vs 2H 2025 (n= ~200-300):
Planned Churn: 8% →18% attributed to AI
Spend Decreases: 17% →27% attributed to AI
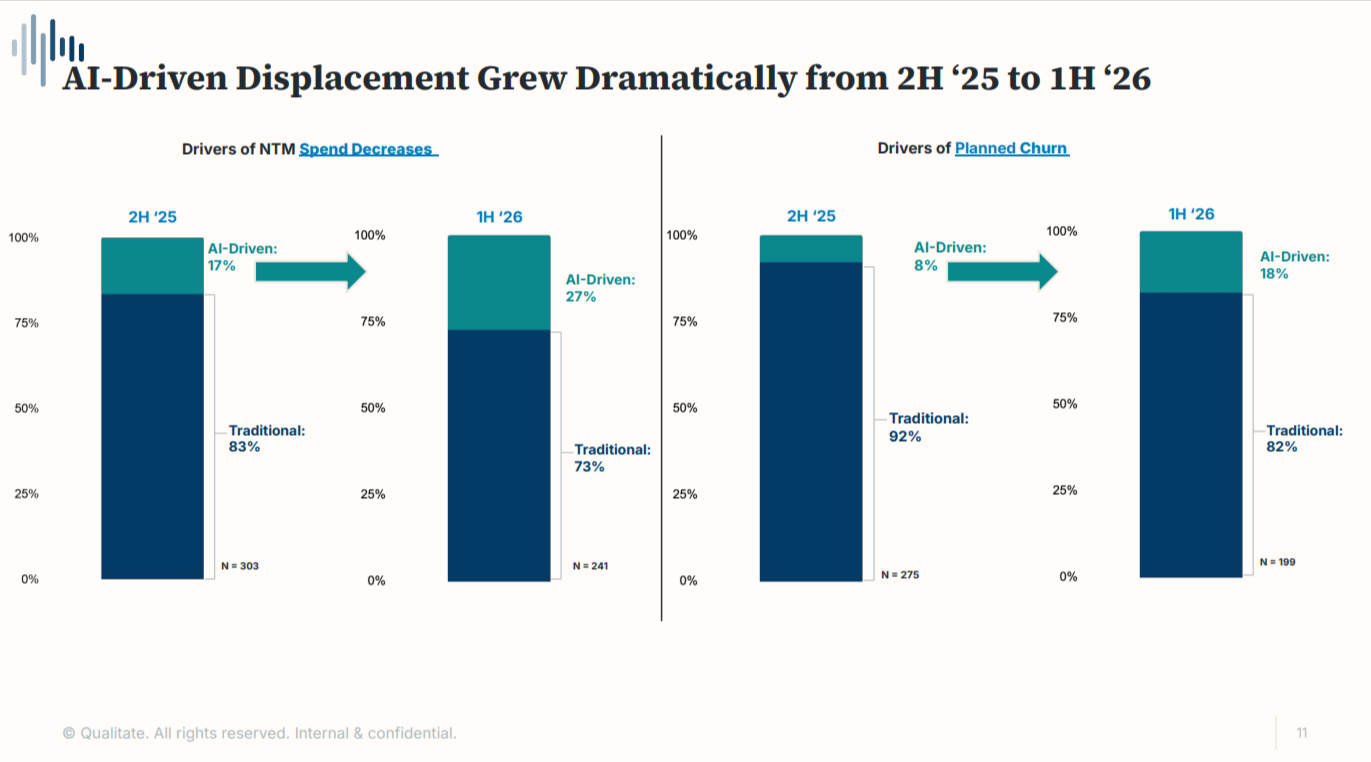
As a caution, the percentages reflected in the above Displacement Reasons (i.e., Spend Decreases and Planned Churn) sample could cause undue alarm.
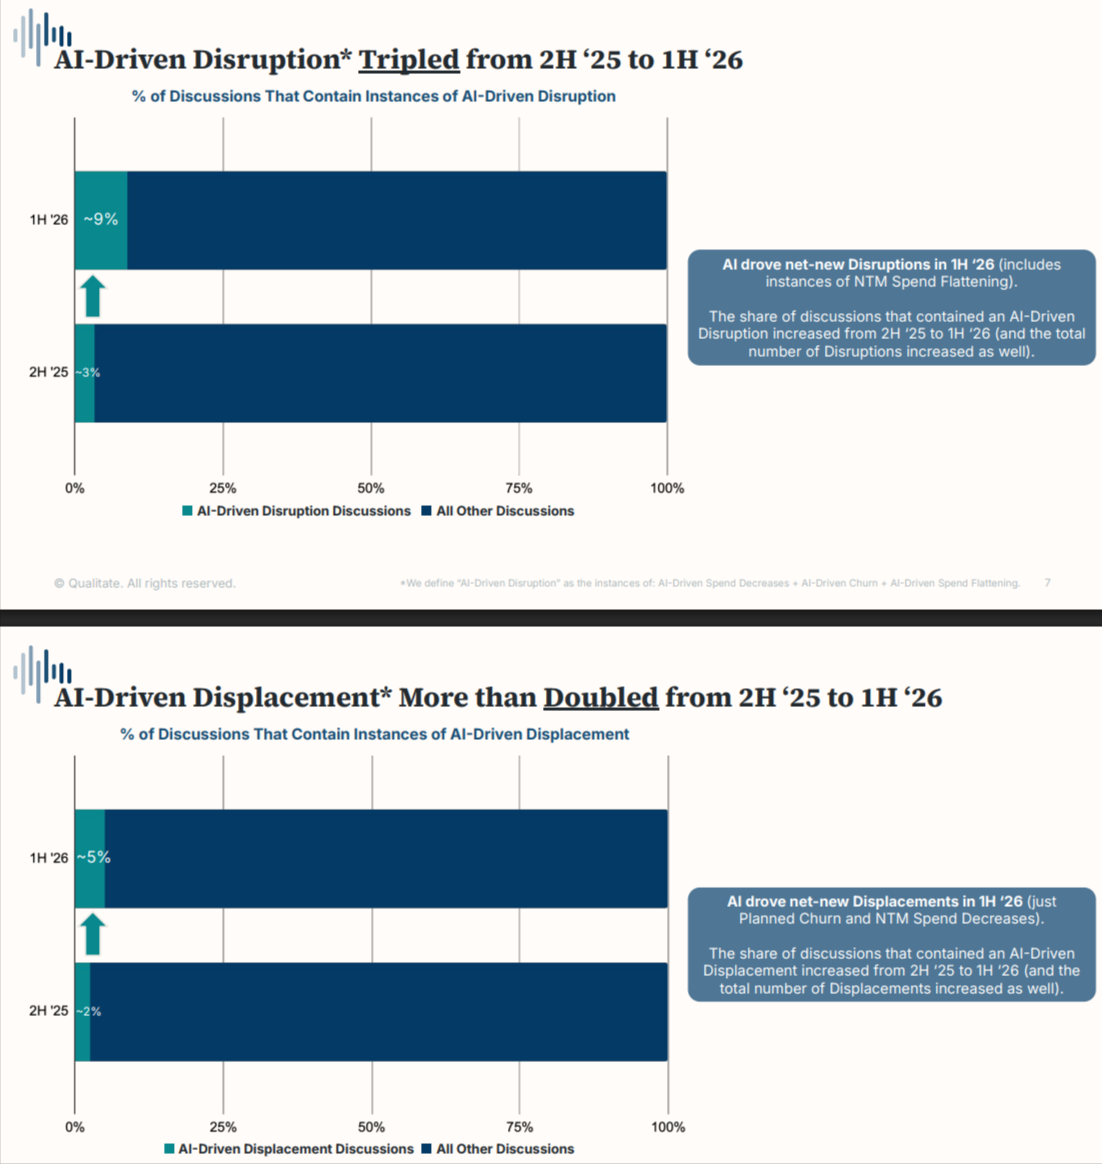
Across all discussions within Qualitate’s broader IT buyer pool (n=4,800+), AI-led headwinds are much lower in absolute terms, albeit growing rapidly:
Disruption All Interviews: 9% (up 3x vs 2H’25)
Displacement (aka Decrease and/or Churn) - All Interviews: 5% (up 2.5x vs 2H’25)
As always with software, it's better viewed at the workflow and category level.
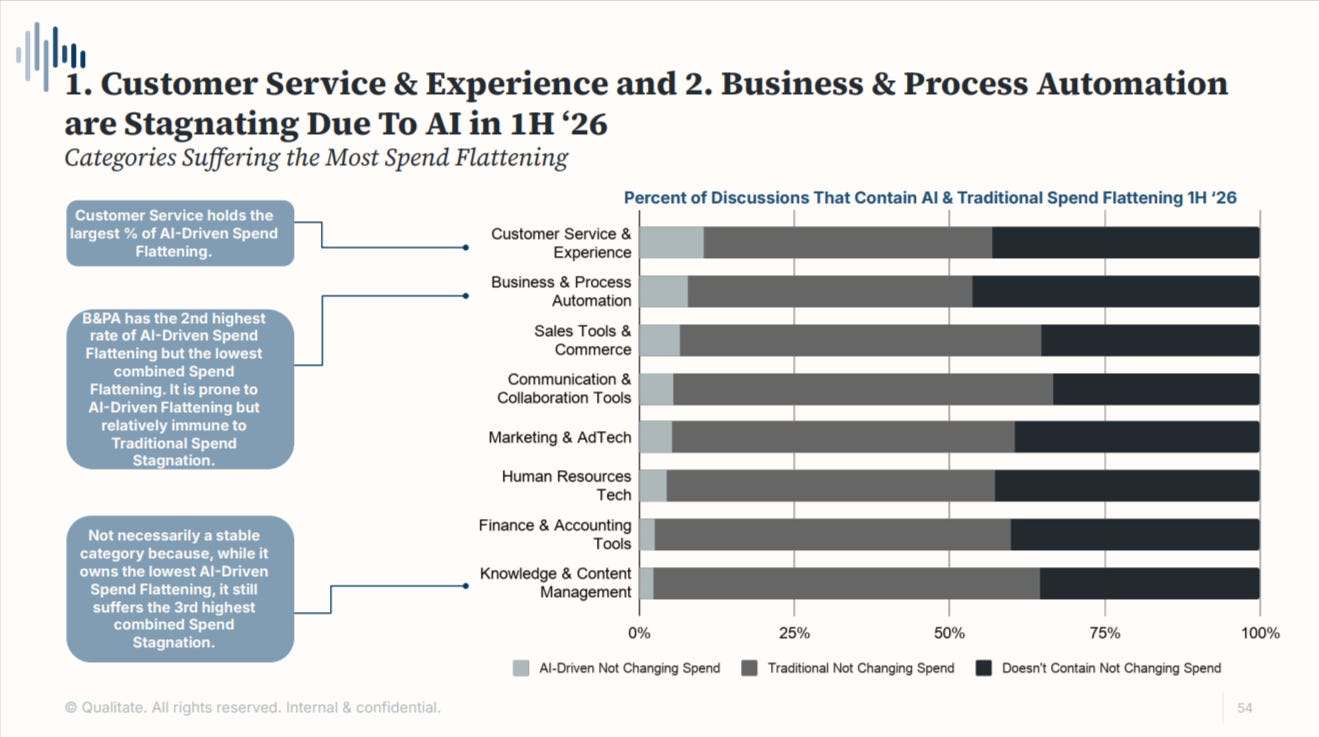
Unsurprisingly, “obvious” areas with compelling AI-Natives are showing flattening of traditional spend (i.e., Customer Service, Business Process), while areas like Finance & Accounting are far less impacted:
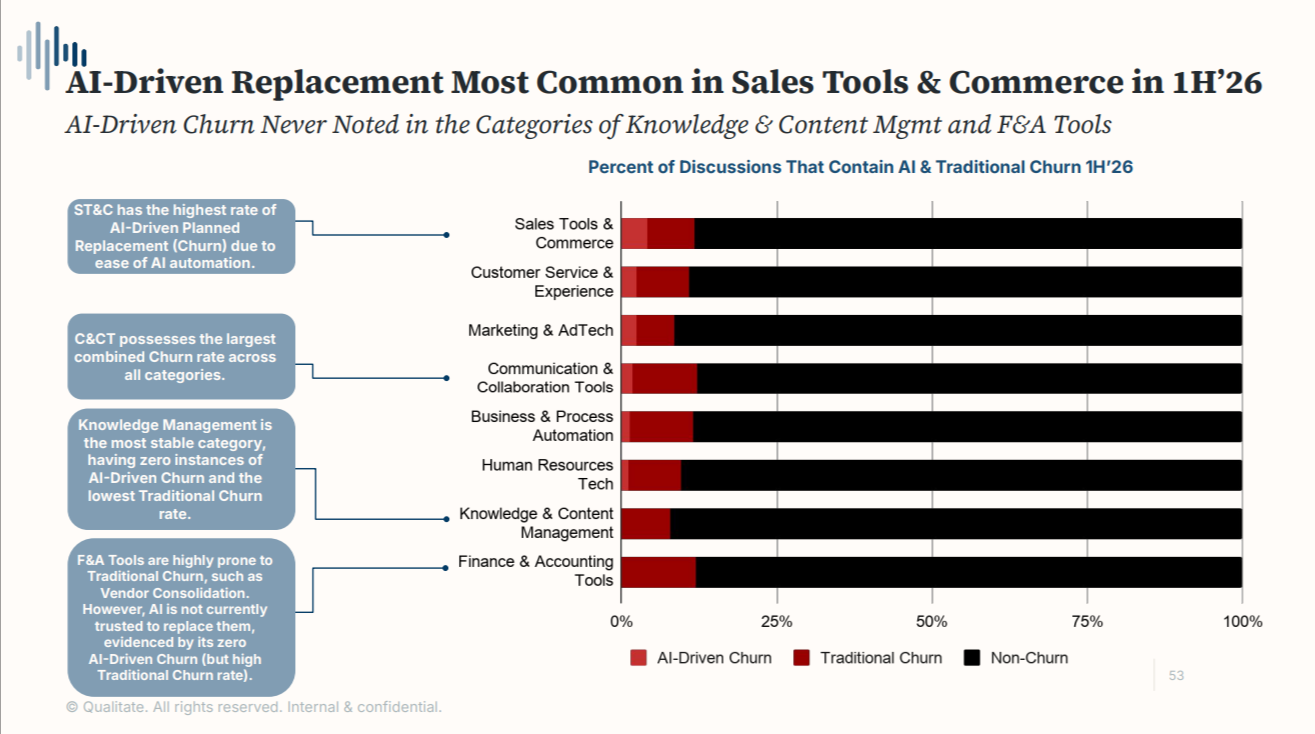
Consensus narratives also seem to hold for this churn discussion by category chart:
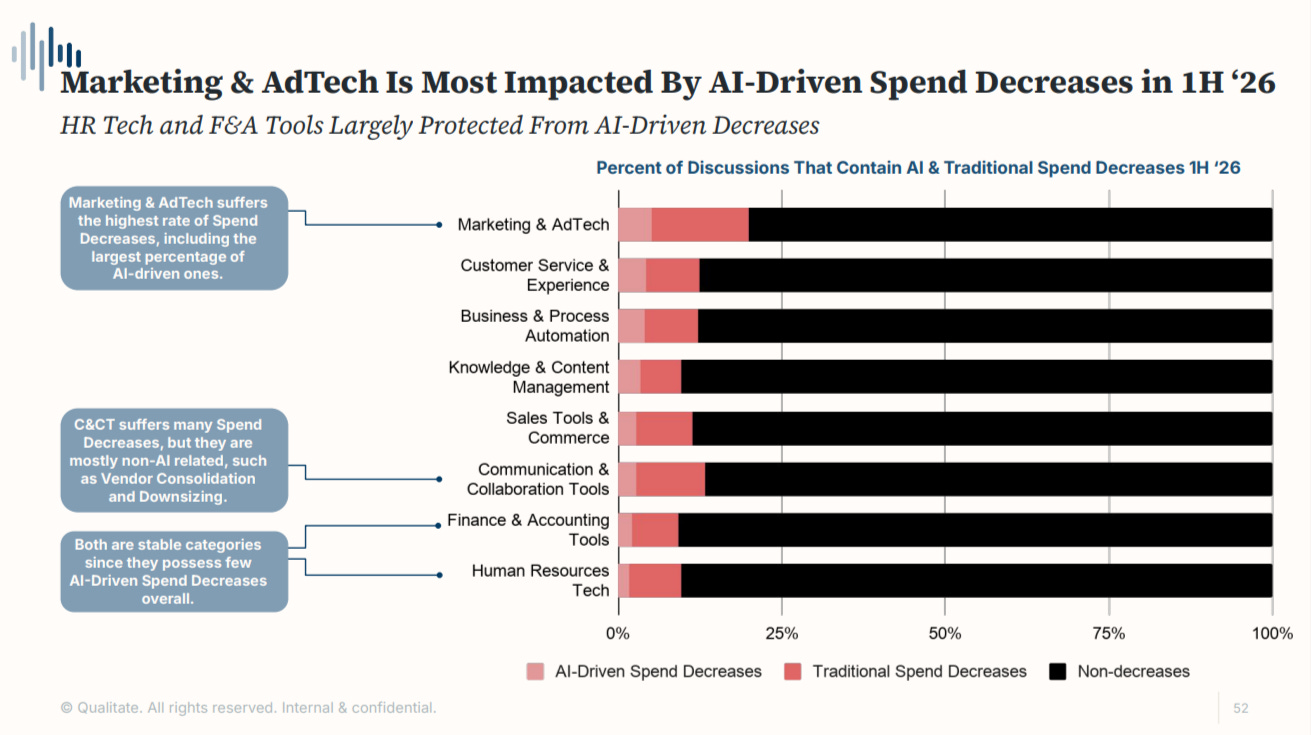
… as well as spend decreases:
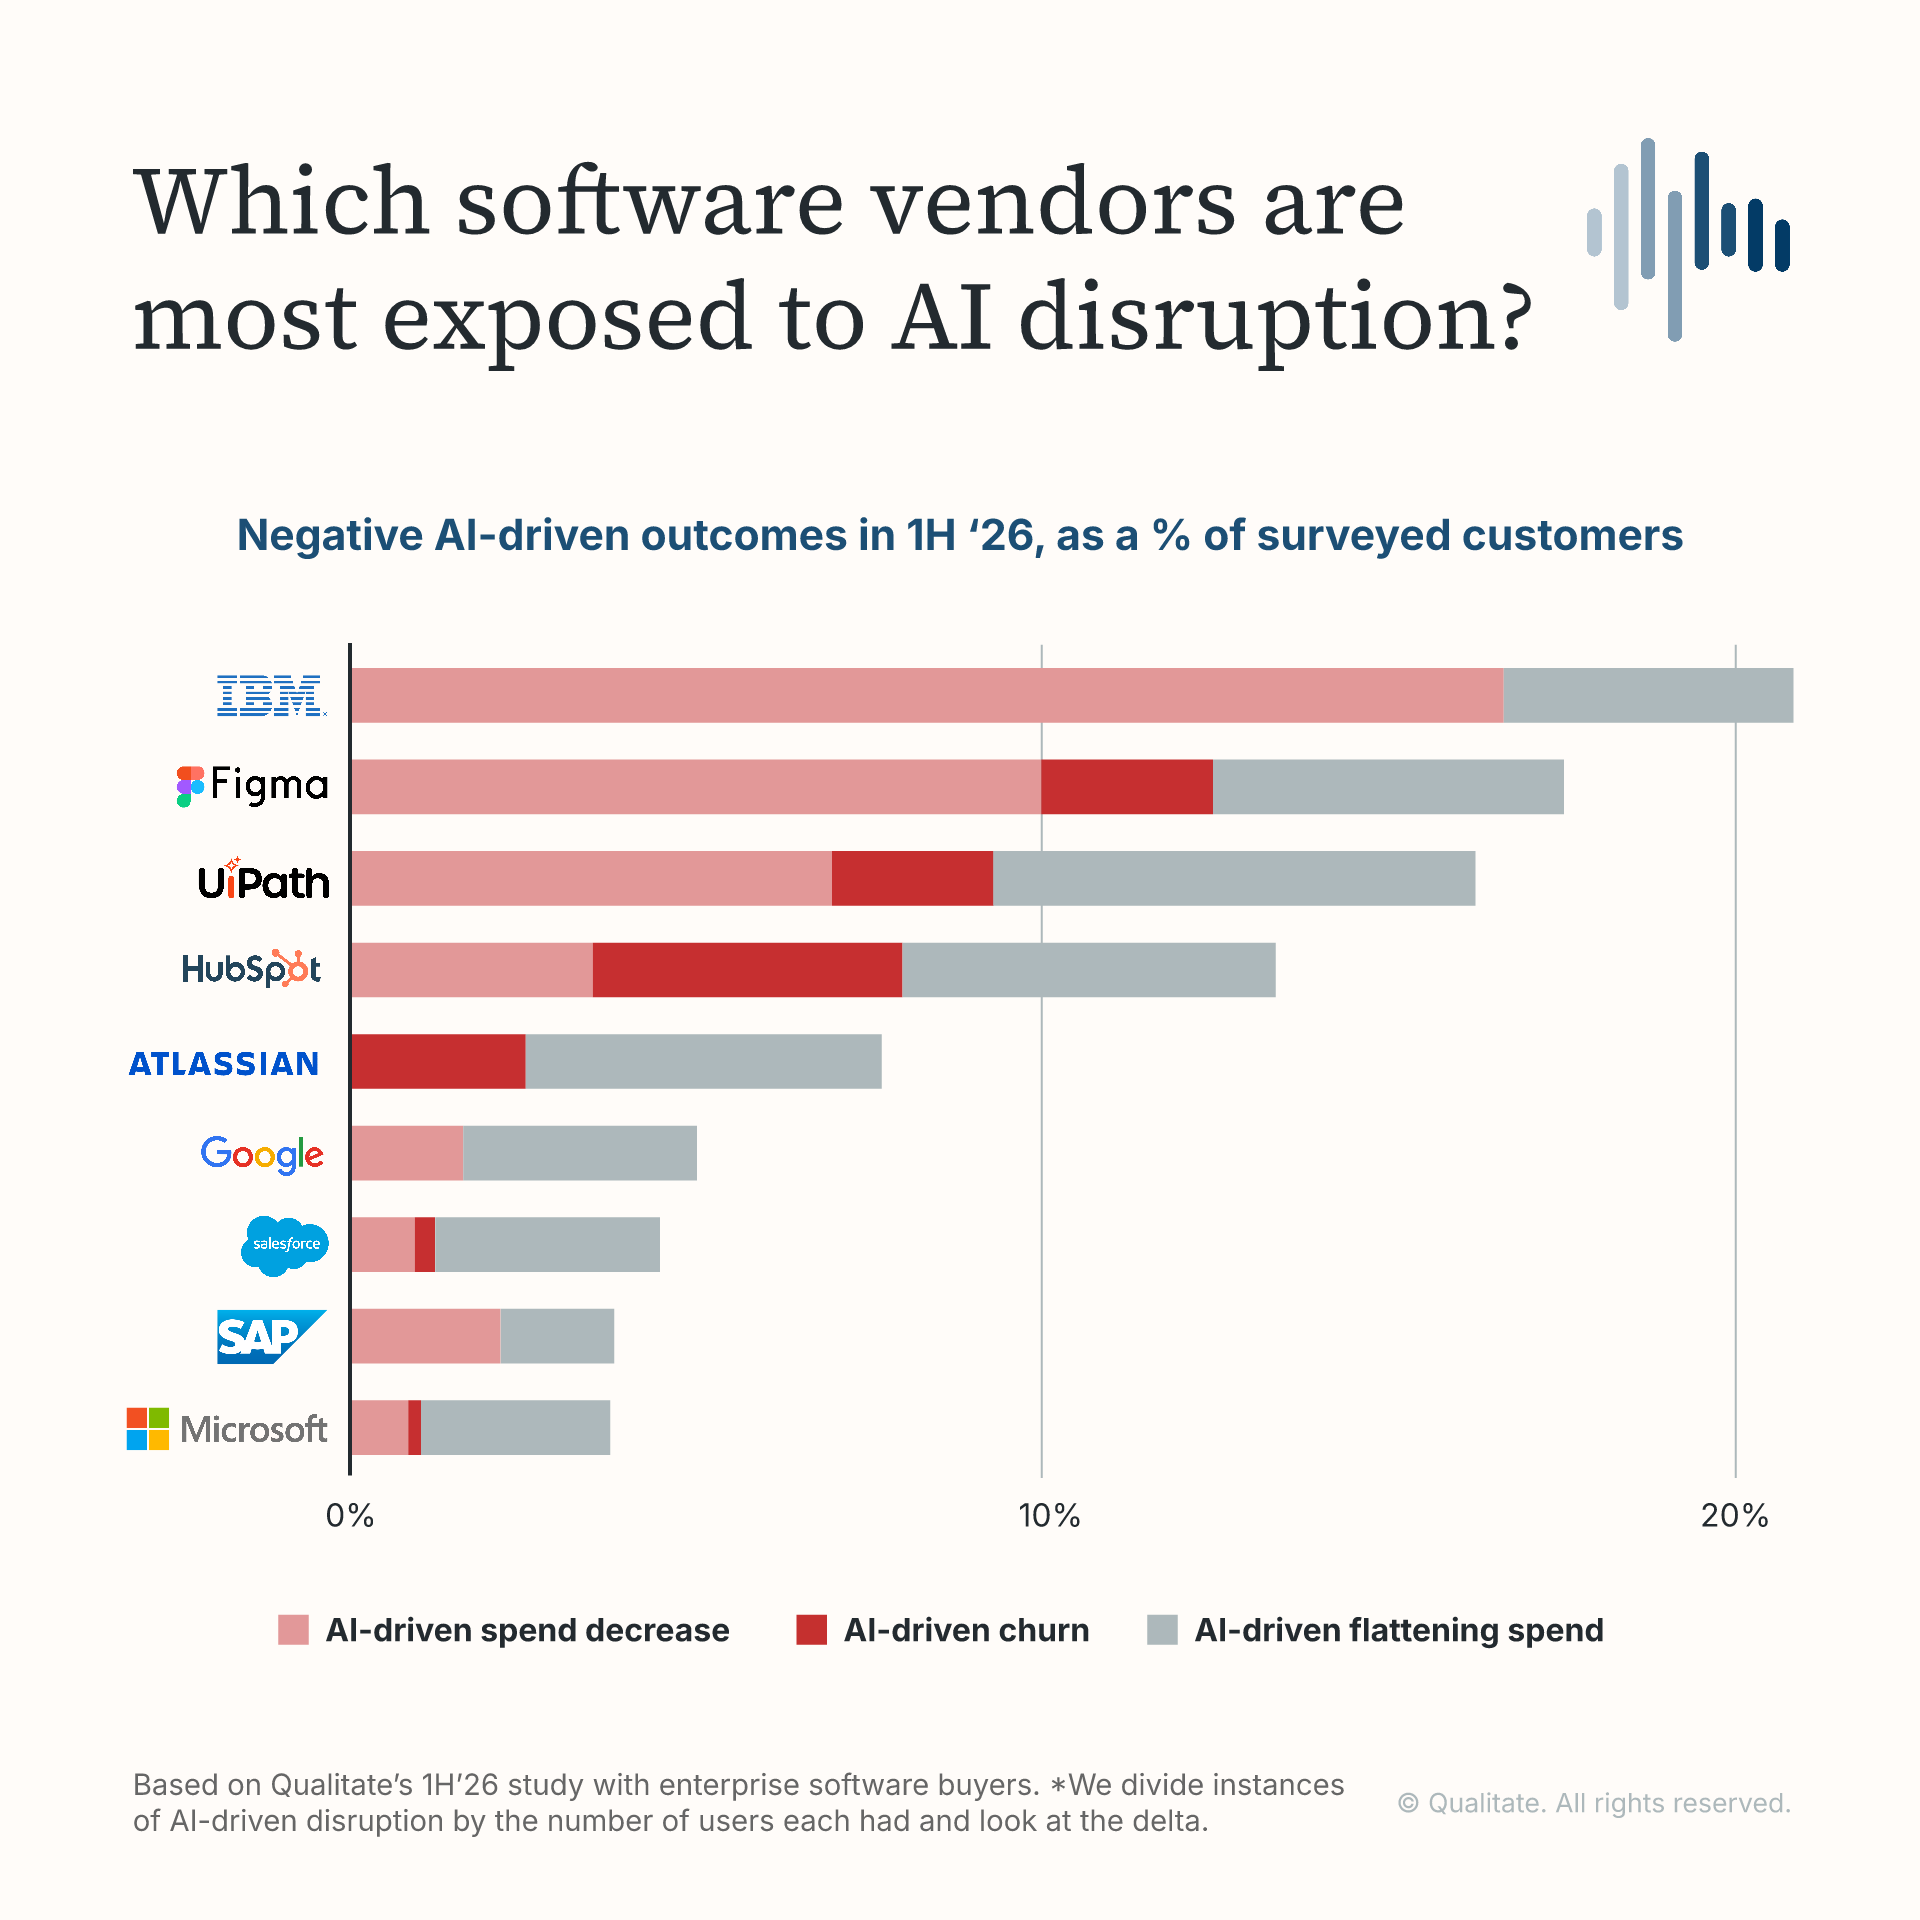
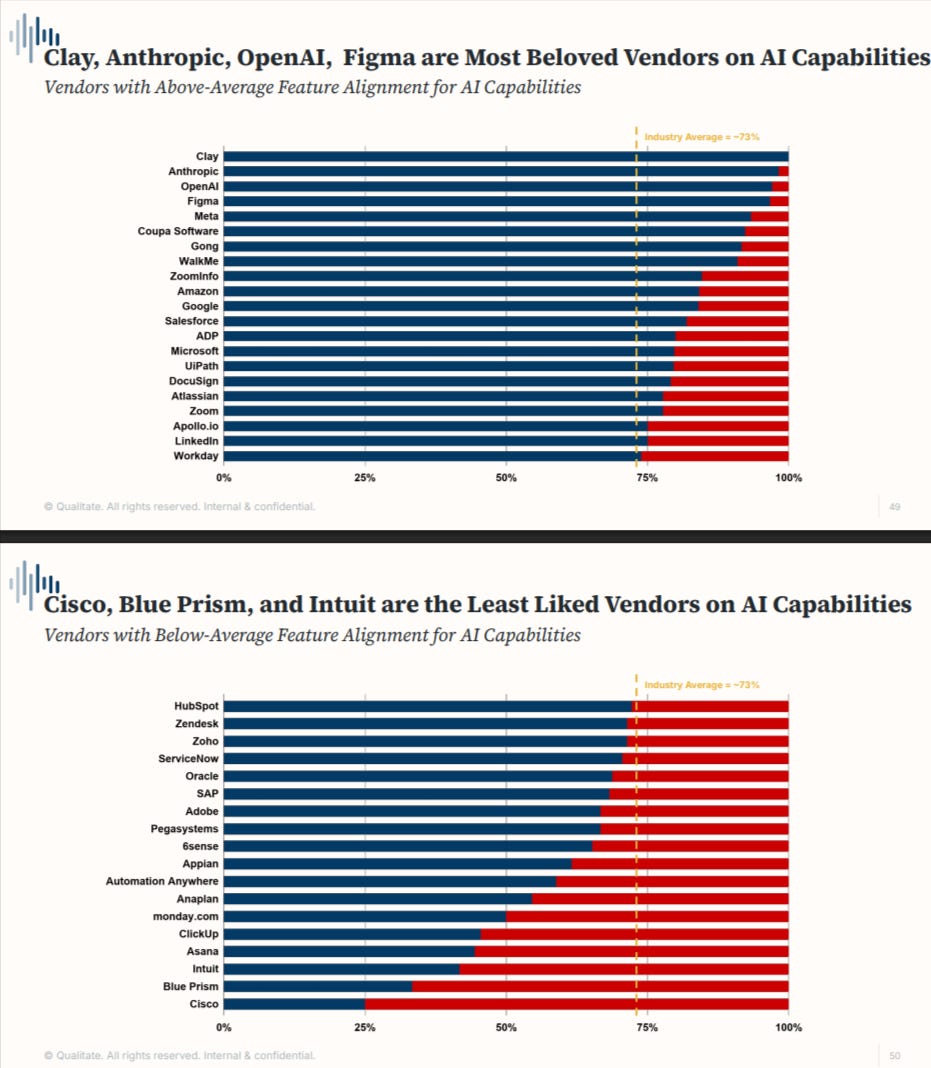
The Qualitate report has extensive specific company coverage - partial examples here:
AI-Led Software Churn As A Funding Mechanism
I strongly believe many audiences - whether operators or investors - overestimate the growth rate of IT budgets (in aggregate + for software). Morgan Stanley’s latest CIO survey reflects 2026e budget growth of:
Software: +4.1%
Overall: 3.8% (via Hardware at 1.6%, Communications at 2.6%, Services at 1.8%)
Given the outsized growth of AI-Natives - like the 130% NRR with 165% YoY ARR growth in the >$100m top quartile cohort covered last week via ICONIQ data - those expansions and new deployments need funding.
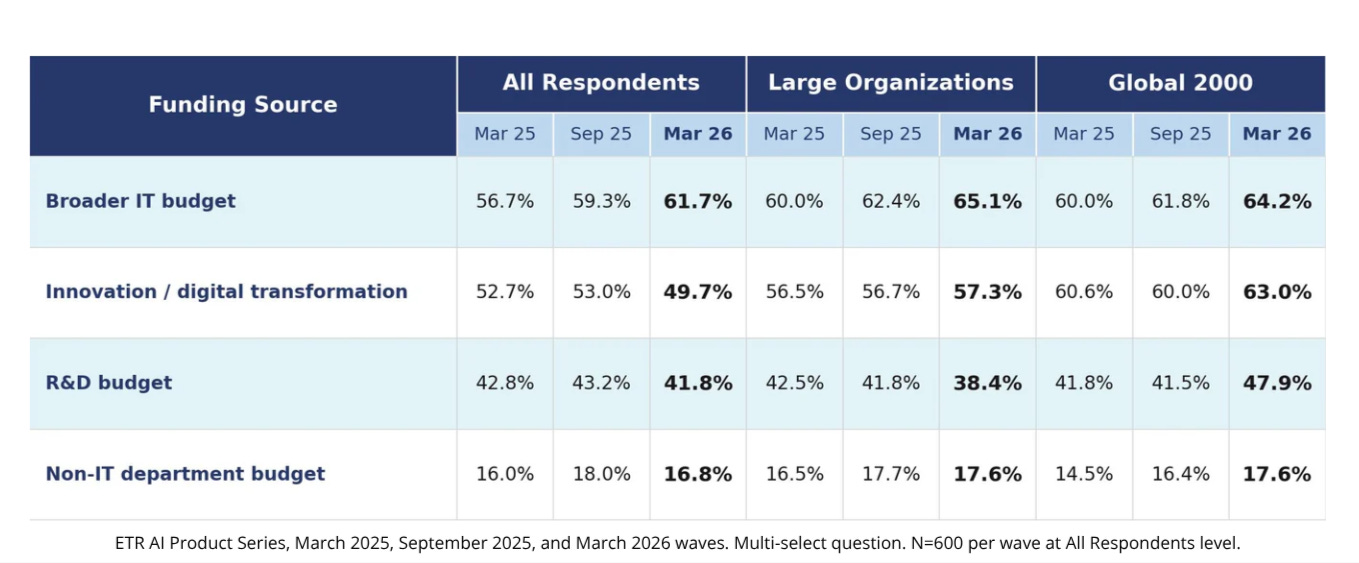
ETR surveys provide excellent data on AI funding mechanisms, especially “Where AI Money Comes From: The Quiet Shift Inside IT Budgets.”
For Large + Global 2000-sized organizations, a) “Broader IT Budget” is the #1 AI funding source and b) the importance of “Broader IT Budget” is generally gaining share versus “Innovation” and “R&D” budget mechanisms.
In the event of AI cost overruns, ETR data specifically calls out 39% of organizations reallocating from other parts of the IT budget.
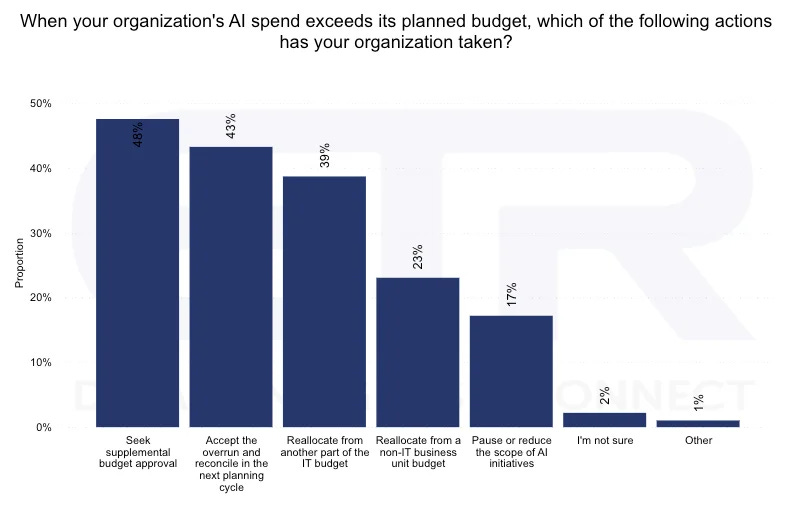
This provides more context for the AI-led churn/spend-flattening data covered by Qualitate.
“Accurate Insights 2026” Event - RSVP Now
Curated for institutional investors, the event will focus on generating actionable, reliable signals from quantitative and qualitative sources in an AI world.
Edward Robson (CIO - 2717 Partners) On “Cloud Returns” Investing Podcast
SPOTIFY | APPLE | OTHER PODCAST PLATFORMS| VIDEO
We recently released this episode with Edward Robson, Partner + Chief Investment Officer of 2717 Partners. The episode outlines his frameworks for capital allocation in technology and the related impact of AI.
About Cloud Ratings
In mid-2024, we announced a research partnership with G2 - more here:

with this slide showing how our G2-enhanced Quadrants (like our recent Sales Compensation Software) release, this business of software newsletter you are reading, our podcasts, and our True ROI practice area all fit within our modern analyst firm:
